How to file a travel insurance claim that holds up: the documents to collect, a simple claim log and the wording traps behind most denials.
Two days after Christmas 2025, a family from the Northeast arrived at the airport for their flight to Fort Lauderdale and a seven-night cruise. The flight was cancelled in the middle of a winter storm, and no other flight could get them to the ship in time. Their travel insurer denied the claim. The airline had coded the cancellation as “ATC restrictions,” and the insurer treated that as a cause the policy didn’t cover, even though weather was.
They posted the denial on Reddit in February 2026, and the replies were a crash course in how a travel insurance claim works. The cause on paper decides if you’re covered. Your receipts decide how much you get. The policy wording decides the rest.
Quick Answer
Tell your airline, hotel and tour operators you’re canceling as soon as you know, and ask the airline for the delay or cancellation reason in writing. Keep every receipt, refund and credit in one log so you can show your real loss. Submit proof of the covered reason, your prepaid costs and any refunds together. If you’re denied, read the exact exclusion, get better evidence and appeal in writing before you go to your state insurance department.
Table of Contents
Why the reason on paper decides your claim
Travel insurance and credit card trip delay benefits pay for covered reasons, not for bad luck in general. A commenter who said they work in travel insurance put it simply in a September 2026 r/CreditCards thread: the reason for the delay matters more than the hours. Card benefits often limit coverage to causes like weather, equipment failure or strikes. Many standalone policies go further and cover a documented carrier delay, which can include crew shortages.
That’s why “air traffic control” is such a common trap. In July 2026, a Chase Sapphire Reserve cardholder posted that their trip delay claim was denied because the airline blamed air traffic control, even though thunderstorms were in the area. They asked the airline why air traffic control had held the flight. The airline said weather, they appealed with that answer, and the claim was approved.
You can document the cause while you’re still at the gate. The FAA’s National Airspace System Status page lists active ground stops and delays with the reason attached, such as thunderstorms, wind or runway construction. Take a screenshot with the time showing.
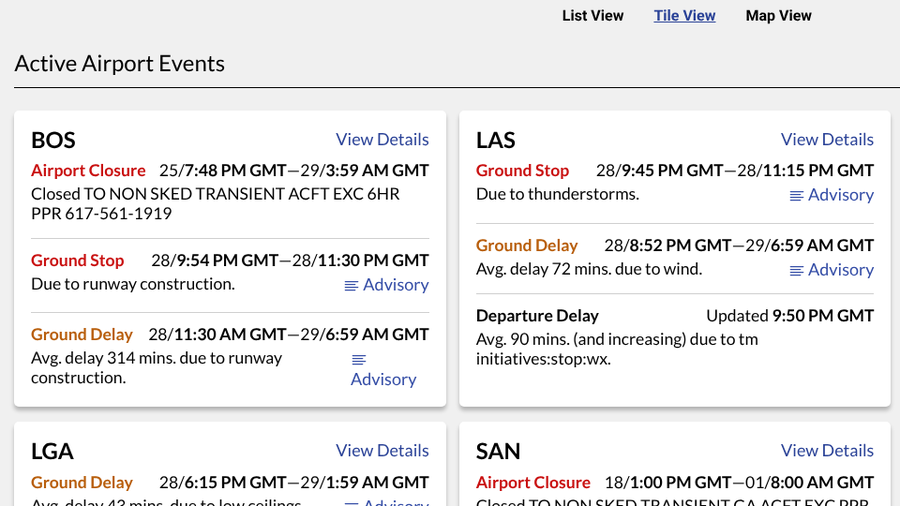
Then ask the airline for a delay or cancellation letter that names the cause. If the app shows “late inbound aircraft,” ask what delayed that aircraft. Our list of screenshots to save before accepting a rebooking covers the rest of what to capture in the moment.
Notify suppliers and gather documents first
Canceling late can cost you even when the reason is covered. Allianz’s guide on how to file a trip cancellation claim says you need to tell travel suppliers within 72 hours of discovering you have to cancel. If you wait longer and your refund shrinks, the policy won’t cover the difference. For an illness, a doctor must advise canceling before you cancel, or examine the sick person within 72 hours afterward.
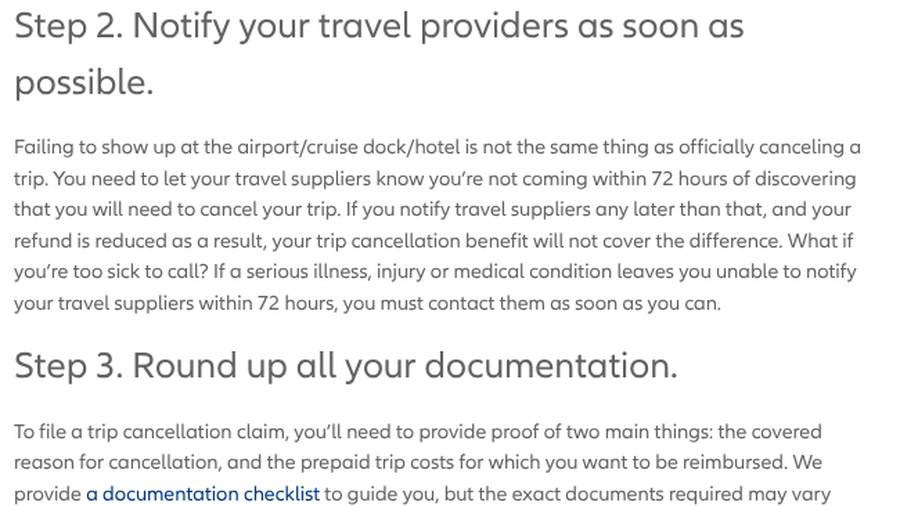
Insurers want two kinds of proof: that the reason is covered, and how much you lost. Collect these before you file:
- The cause: the airline’s delay letter, a doctor’s note or a police report.
- What you paid: itemized receipts plus your original itinerary.
- The rules: each supplier’s cancellation and refund policy.
- What came back: refunds, credits or vouchers you’ve received.
- Extra costs: receipts for meals, hotels or alternate transportation during a delay.
A single card statement usually won’t do. In April 2026, a Reddit user fighting a claim said the insurer had their receipts and card statements but still asked for proof that each booking was cancelled. It also wanted each vendor’s confirmation that the booking was non-refundable. Ask vendors for those emails while you’re already talking to them.
Keep a claim log with a net-loss column
Insurers reimburse what you lost, not what you paid. Allianz, for example, pays for alternate transportation “less available refunds.” A simple spreadsheet keeps that math straight and gives the adjuster one page to check instead of a pile of PDFs. Here’s the shape it should take, with example numbers:
| Date | Vendor | Paid | Refund or credit | Net loss | Proof file |
|---|---|---|---|---|---|
| Dec 27 | Airline | $1,200 | $1,200 refund | $0 | airline-cancel-email.pdf |
| Dec 27 | Airport hotel | $189 | $0 | $189 | hotel-receipt.pdf |
| Dec 28 | Cruise line | $4,800 | $0 | $4,800 | cruise-invoice.pdf |
Add a notes column for claim numbers, call dates and the name of anyone you spoke with. Claim the airline refund you’re owed before you claim it from the insurer, since insurers subtract refunds from your payout anyway. Our guide to airline and hotel refund rules explains when that money is yours.

Denials you can see coming
Some denials are decided the day you buy the policy.
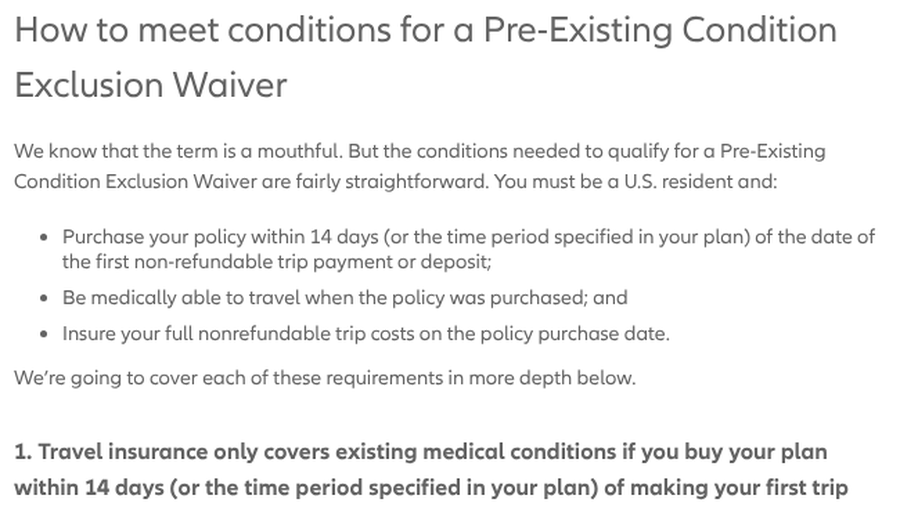
Pre-existing conditions. Allianz defines an existing medical condition as one that led to treatment, showed symptoms or needed a medication change in the 120 days before you bought the plan. To get it covered, Allianz’s pre-existing condition waiver requires buying within 14 days of your first nonrefundable trip payment and insuring your full nonrefundable costs. Other insurers use windows of up to about three weeks. In June 2026, a traveler on Reddit wrote that they’d missed that window after their first deposit because they’d never bought travel insurance before.
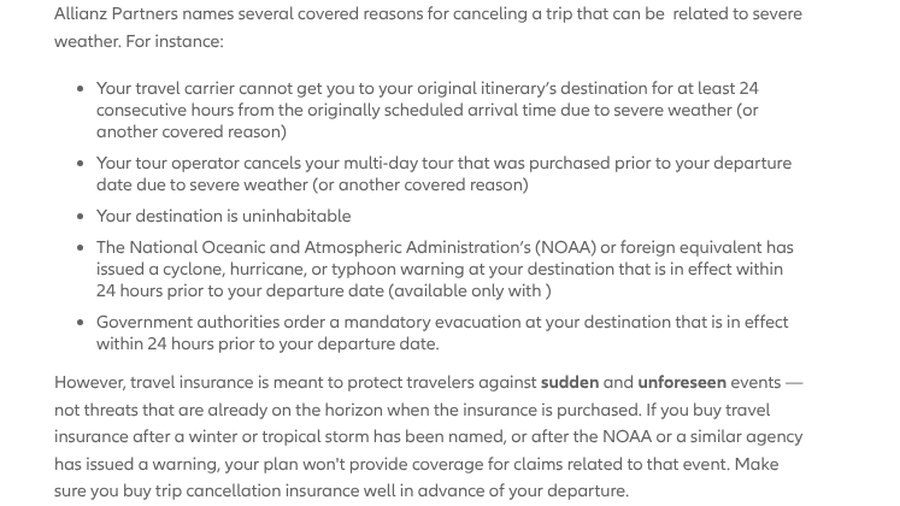
Foreseen events. Allianz’s list of reasons trip cancellation claims are denied warns that a plan bought after a storm is named, or after a NOAA warning, won’t cover claims tied to that storm. It also warns against canceling too soon. For a trip cancellation claim, your carrier must be unable to get you to your destination for at least 24 consecutive hours.
War and system-failure exclusions. In April 2026, an Australian traveler stranded by the Middle East conflict posted that their card’s travel insurance denied the claim under its war clause. In September 2026, a British Airways passenger whose flight was cancelled after the September 8 air traffic control disruption said their insurer cited an exclusion for computer system errors. Another traveler, whose bank’s policy was underwritten by the same insurer, said theirs paid out in about a week. Two policies from one underwriter gave different answers, so read your own wording.
How to appeal a denied travel insurance claim
- Get the denial in writing with the exact clause the insurer relied on.
- Read that clause and its definitions. “Weather” and “air traffic control” may be defined differently from how you’d use them.
- Close the evidence gap. Ask the airline to restate the cause in writing, and add FAA screenshots, a doctor’s letter or vendor emails.
- Appeal in writing, briefly, with the new evidence attached and your claim number on every page.
- Escalate to your state regulator if the insurer won’t budge. The NAIC keeps a directory of state insurance departments.
Slow payment deserves the same treatment. In September 2026, an Allianz customer posted that an approved claim of about $600 still hadn’t arrived months after it was filed in June. They filed a complaint with the Texas Department of Insurance and asked for interest. Commenters suggested double-checking the bank details on file first, since a payment can go to the wrong account.
This article is general information and isn’t legal or insurance advice. Coverage, exclusions and deadlines vary by policy and state. Read your policy documents and contact your insurer, or your state insurance department, about your specific claim.
What To Do Next
- Get the delay or cancellation cause in writing and screenshot the FAA status page while you’re stuck.
- Tell every supplier you’re canceling within 72 hours of knowing.
- Track paid amounts, refunds and net loss in one log with a proof file for each line.
- Buy coverage within 14 days of your first deposit if you need a pre-existing condition waiver.
- Appeal denials with new evidence before going to your state insurance department.
Frequently Asked Questions
What documents do I need for a travel insurance claim?
You need proof of the covered reason, such as an airline delay letter or doctor’s note. You also need itemized receipts, your itinerary, each supplier’s refund policy and proof of any refunds or credits you received.
How long does a travel insurance claim take?
It depends on the insurer and how complete your file is. Allianz asks customers to allow 10 business days for review after filing and says direct deposit pays faster. Missing documents restart the wait.
Does travel insurance cover flight cancellations?
It can, if the cancellation is for a covered reason such as severe weather. Allianz’s trip cancellation benefit applies when your carrier can’t get you to your destination for at least 24 consecutive hours. Claim your airline refund first, since insurers deduct it.
Why was my travel insurance claim denied?
Common reasons include a cause the policy doesn’t cover, a pre-existing condition without a waiver and an event that was foreseeable when you bought the plan. Missing paperwork and late notice to suppliers also sink claims.
Can I appeal a travel insurance claim denial?
Yes. Ask for the denial in writing, answer the specific clause with new evidence and appeal in writing. If that fails, file a complaint with your state insurance department.
Final Takeaway
A travel insurance claim is won or lost on paper, often before you get home. Get the cause in writing while you’re at the airport and keep a clean log of what you paid and what came back. Know which exclusions your policy has before you need it, and don’t treat the first denial as the last word.
Related Posts